The General Insurance® App

Screenshots
Details
- Rating
- 10.90K reviews
- Version
- 8.1.0
- Developer
- The General Automobile Insurance Services, Inc
Analysis by Norviv
Buying or managing car insurance is rarely something I want to turn into a daily habit, so I approached The General Insurance® with a practical question: does it remain useful after the first quote or policy check? My experience is that it works best as a focused companion for people who already use The General and want insurance tasks available on a phone, rather than as a general-purpose tool for comparing every insurer.
The app comes from The General Automobile Insurance Services, Inc and sits in the Business category. It is free to install, rated for Everyone, and has been available since April 11, 2012. Its current version is 8.1.0, and it runs on Android devices using version 6.0 or later. Those details matter because this is not a brand-new experiment; it is a mature insurance app that has had time to settle into a specific job.
What The General Insurance® feels like after the first week
The first-week appeal is straightforward. Instead of keeping insurance paperwork buried in an email account or glove compartment, I can use a phone-based starting point for the tasks that normally make me reach for a browser or call an agent. That makes the app most attractive when I am already a customer, need to review policy information, or want to handle a routine insurance matter away from a desktop.
I would not describe it as an app that rewards exploration for its own sake. Its value comes from reducing the distance between a question and the relevant insurance account. That is a good design priority for this category. People do not open an insurance app to browse; they open it because they need an answer, a document, or an action completed without unnecessary delay.
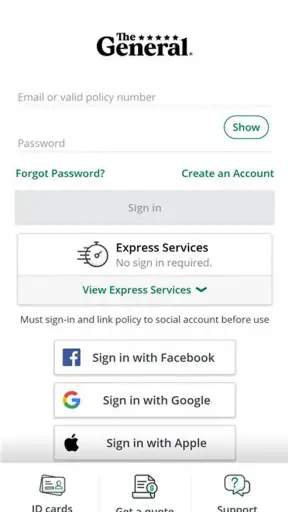
During an ordinary first-week test, I would begin by signing in, checking that the policy and vehicle details look familiar, and looking for the most common account actions. This is a useful habit before an emergency occurs. If I wait until I am standing beside a damaged car or speaking with another driver, even a reasonably clear interface can feel stressful. A quiet first check tells me where the important information lives.
The app’s broad audience is also easy to understand. With more than a million installs and an average rating of 4.7 from roughly forty thousand ratings, it has reached far beyond a small group of early adopters. That does not guarantee that every insurance situation will feel smooth, but it does suggest that the basic mobile experience has earned meaningful trust from people using the service.
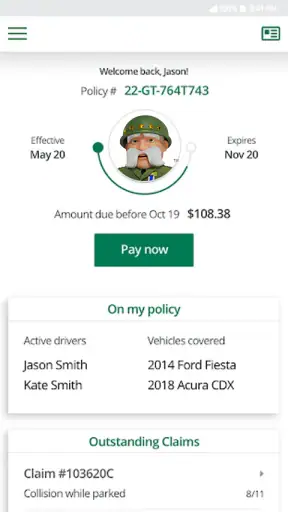
One useful first-week workflow is to treat the application as a digital readiness check rather than merely a place to look at a bill. I would confirm that I can sign in, identify my active vehicle and coverage information, and locate the route for getting help. Doing this before a road trip is more sensible than installing the app after something goes wrong. It also exposes account problems while there is still time to solve them calmly.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
The main limitation appears quickly as well. This is tied to The General’s insurance ecosystem, so it is not a neutral marketplace where I can place policies from several companies side by side. If my main goal is to compare deductibles, exclusions, customer service reputations, and prices across insurers, a comparison website or direct visits to several providers may be more appropriate. The app is about managing a relationship, not replacing the entire shopping process.
Where it helps in an everyday situation
Imagine lending my car to a family member before a weekend trip. I would rather review the relevant policy information in advance than rely on a vague memory of what is covered. The app can serve as a convenient place to begin that check, especially when I am away from home and do not have printed documents nearby. The important point is not that a phone screen removes every insurance question; it gives me a faster starting point for the questions that still need attention.
Another realistic moment is moving between vehicles or dealing with a change in routine. I may be parking at a different address, preparing for a longer drive, or trying to confirm that my account details are current. A mobile account makes those checks easier to fit into the day. I can handle them while the information is fresh instead of postponing them until I remember to sit at a computer.
That convenience has a boundary. Insurance language can be precise, and an app interface cannot turn every coverage condition into plain certainty. I would still read the policy wording and contact the insurer when a decision has financial consequences. The app is a useful access point, not a substitute for understanding the contract.
Why it can keep earning space month after month
The long-term value of an insurance app is measured in small moments. I may use it only when a payment, document, vehicle detail, or claim-related question comes up. That low frequency is not a weakness by itself. In fact, a good insurance app should be quiet most of the time and dependable when I need it.
For an existing customer, the recurring benefit is having account access in the same place as other essential phone tools. I do not need to remember which browser bookmark contains the insurer’s website, and I am less likely to lose a paper document. The app becomes worthwhile when it shortens a task that would otherwise involve searching through messages or navigating a full desktop site.
I also like the idea of using it as a monthly account checkpoint. Rather than opening it only during a crisis, I can occasionally verify that my policy information still matches my situation. This is especially useful after a change involving a vehicle, household, address, or driving pattern. The check itself may take little time, but it can prevent an outdated assumption from becoming a problem later.
That said, the application will not create a reason to open it every day. There is no sensible need for constant engagement with car insurance, and I would be suspicious of any product that tried to manufacture it. Its lasting value comes from being available at the right moment, not from notifications or a forced routine.
The developer’s long presence in this space also shapes my expectations. A mature insurance application should be judged less by novelty and more by whether it remains dependable through ordinary account changes. Version 8.1.0 indicates ongoing development, but I would still evaluate updates by practical improvements: clearer account information, fewer confusing steps, and reliable access when I am not at home.
For someone who rarely changes vehicles and has a stable policy, monthly use may be minimal. That person might prefer the insurer’s website if they already find it easy and do not want another app. The mobile version earns its place when convenience, document access, and on-the-go account checks matter enough to outweigh the extra icon on the home screen.
Maintenance without turning insurance into a chore
The maintenance burden is fairly easy to underestimate. Installing the app is the simple part; keeping the account useful requires accurate personal and vehicle information. I would not assume that opening the app once proves everything is current. After a major life or driving change, I would review the account and contact The General if the situation is not represented clearly.
My practical advice is to keep the app available before it becomes urgent, but avoid treating it as a permanent background project. Sign in when a policy event is approaching, after a relevant personal change, or before a trip where access to insurance information could be valuable. This creates a light maintenance rhythm without wasting time on repetitive checks.
Security habits matter too. Because the app concerns insurance and personal account information, I would use a strong device lock and avoid signing in on a shared phone. I would also be careful when reading messages that appear to request account action. The application can make access more convenient, but convenience should not mean ignoring ordinary account-safety practices.
Another maintenance issue is device compatibility. The minimum operating system is Android 6.0, which covers many older phones, but users on aging hardware should still expect the experience to depend on their device and system condition. Keeping the operating system and the app updated is sensible, particularly for an application used to access important documents or account details.
There is also a human maintenance step that no mobile interface can remove: knowing when to ask for help. If a policy change is complicated, a claim involves several parties, or the wording affects a significant financial decision, I would use the app to find the next step and then speak with the insurer. Trying to force a complicated situation through a quick screen can create more frustration than it saves.
Where fatigue can set in
The biggest source of fatigue is repetition. Insurance accounts are full of familiar details, and if I have to re-enter information or move through several screens for a simple check, the app quickly loses its advantage over a browser. A mobile experience should reduce friction, not merely place the same paperwork on a smaller display.
A second source is expectation management. The store summary presents affordable car insurance as the central promise, but an account app cannot determine whether a particular driver will receive the right price or coverage for every situation. I would not judge the application solely by the quote or policy outcome. Those depend on insurance circumstances, while the app should be judged by how clearly it helps me manage what I already have.
This distinction is important when comparing it with alternatives. A direct insurer app generally offers a more connected experience for that company’s customers than a broad comparison tool. A comparison service is better for shopping around, while a desktop portal may be better for reading long policy documents or handling complex changes. The General’s app is strongest in the middle: more convenient than searching for account pages, but not a replacement for independent research or detailed human support.
I would also avoid assuming that every important answer belongs inside the app. Some insurance questions are interpretive rather than administrative. For example, I may need to understand how a particular incident affects coverage, whether a change must be reported immediately, or which documents are required. Those questions deserve careful clarification. The app can help me reach the insurer, but it should not encourage false confidence from a short summary.
Another possible fatigue point is infrequent use. If I open the application only a few times a year, I may forget the sign-in process or where a particular document is located. That is why my first-week setup recommendation is valuable: learn the basic path when nothing is urgent. A small amount of preparation makes occasional use feel much smoother.
For drivers who want extensive planning tools, policy education, or a single dashboard for multiple insurance providers, this may feel limited by design. It is not a personal finance manager, a vehicle maintenance tracker, or an independent advice service. Choosing it means accepting a narrower purpose in exchange for a more direct connection to The General.
My long-term verdict on keeping it installed
After the novelty fades, The General Insurance® earns lasting space when I have an active relationship with The General and value quick mobile access to insurance tasks. Its strongest quality is not entertainment or constant engagement; it is readiness. When I need to check an account, prepare for a trip, or locate the next step in an insurance matter, a dedicated app is more convenient than beginning from a blank browser tab.
I would recommend it to existing customers who prefer handling routine business from a phone, drivers who want to prepare before an emergency, and people who regularly move between home, work, and travel. It is also a reasonable choice for anyone who dislikes keeping insurance documents scattered across email, paper folders, and browser history.
I would be more cautious about recommending it to someone still deciding which insurer to choose. The app does not remove the need to compare coverage carefully, read terms, or ask questions about a quote. A comparison-focused service or direct conversations with several insurers will be better for that stage. Likewise, users who rarely use mobile apps and are already comfortable with a desktop portal may gain little from installing another account tool.
My best tip is to install it before you need it, complete the initial sign-in while you are calm, and make a note of where the key account information and support route are located. My second is to revisit the account after any meaningful change to your vehicle or personal circumstances rather than assuming yesterday’s details still apply. My third is to treat the app’s information as a starting point for decisions, not as a replacement for the full policy or a qualified explanation.
The free price makes trying it low-risk, and the Everyone rating keeps its intended audience broad. With around eleven thousand written reviews alongside its strong average rating, the app has enough public adoption to feel established rather than experimental. Still, popularity does not change its central trade-off: it is valuable because it is specialized.
In the end, I see The General Insurance® as a practical utility rather than an app I would open for fun. It does not need to become part of my daily routine to justify itself. If it saves me from hunting through paperwork during the few moments when insurance information matters, it has done its job. Its lasting value comes from dependable access at inconvenient times, not from trying to make insurance more exciting than it is.
Frequently Asked Questions
01What can I do with The General Insurance® App?
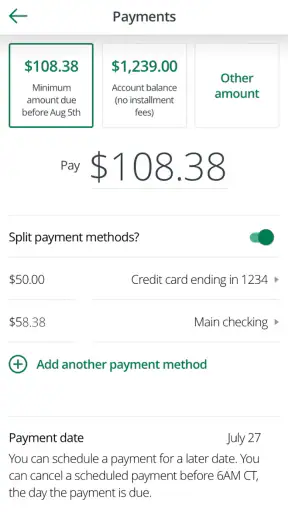
The General Insurance® App is designed to help policyholders manage their auto insurance from a mobile device. Depending on your policy and state, you can typically view policy information, access digital insurance cards, make payments, review billing details, request assistance, and contact customer support. Available features may vary, so check the app after signing in to see which services are enabled for your account.
02Can I make an insurance payment through The General Insurance® App?
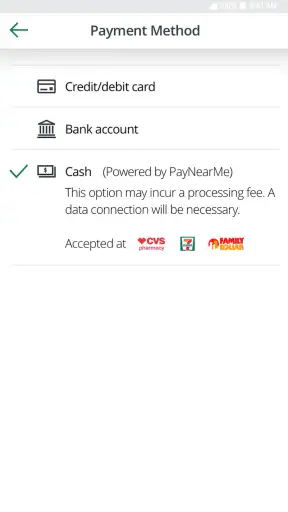
Yes, the app generally allows eligible customers to make insurance payments and review payment or billing information. Before submitting a payment, carefully verify the amount, due date, and selected payment method. Processing times, accepted payment options, fees, and policy requirements may differ by account and location. A successful in-app payment does not necessarily replace any separate confirmation from your bank.
03Does the app provide digital proof of insurance?
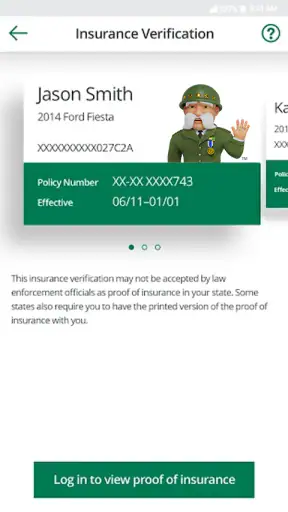
The General Insurance® App may provide access to digital insurance cards or other policy documents, allowing you to keep proof of coverage on your phone instead of carrying paper copies. Availability can depend on your policy, state regulations, and account status. It is wise to download or save documents when possible and keep a backup, especially before driving in areas with limited internet access.
04Is The General Insurance® App safe to use?
The app is intended for customers to manage sensitive insurance and payment information, so users should download it only from the official Google Play Store or Apple App Store and confirm the publisher before installing. Use a strong, unique password, enable device security, and avoid signing in on public or unsecured networks. Never share verification codes or account credentials with anyone.
05Who can use The General Insurance® App, and what should I do if I cannot sign in?
The app is primarily intended for existing The General policyholders, although registration and available services may depend on your policy, state, and account information. If sign-in fails, check your credentials, update the app, and confirm that your internet connection is working. Use the password-recovery option if available, or contact The General through its official support channels for account assistance.


